The short answer
- To compare your HOA's finances to other HOAs, compare six per-home numbers, not the dues alone: dues, operating spending, the reserve share of the budget, percent funded, the share of homes 60 days behind, and the three biggest contracts.
- Pick three to five true peers (same kind of homes, a similar count, similar amenities, the same county) and fill their numbers from free public sources: the Census county median, any peer's Form 990 on ProPublica, and the budgets many of them send their owners.
- Hold reserves against a fixed line, not the neighbors: 70% funded is strong, and three in four associations in one firm's 100,000+ reserve studies are below it.
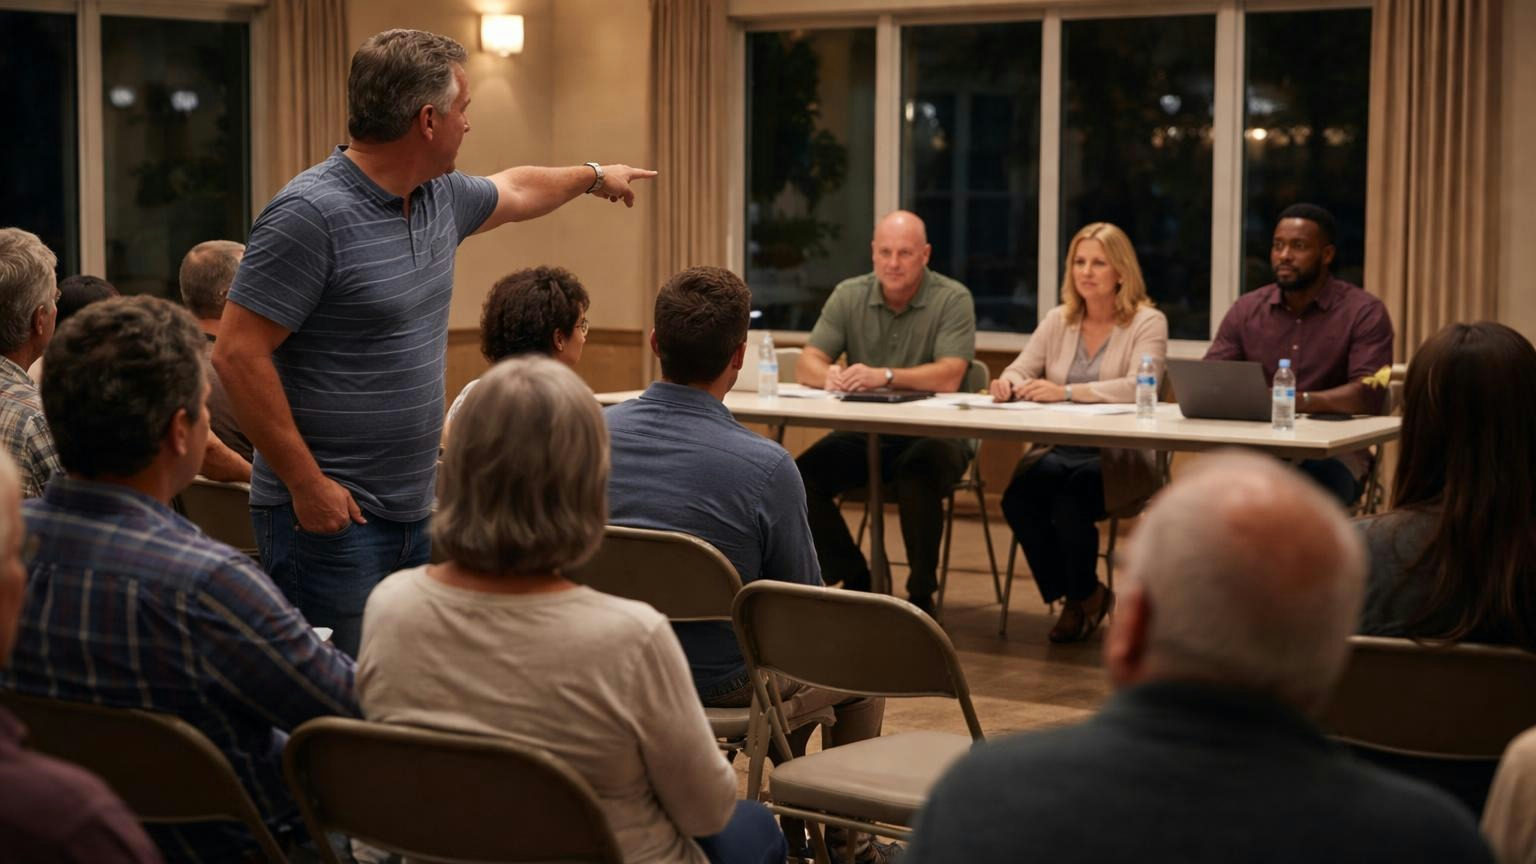
Picture it: the owner in the third row stands up before the treasurer has finished the first page. "Oakmont, down the road, pays sixty dollars a month. We pay eighty-five. Why?"
Nobody at the table knows. Nobody has ever put Oakmont's numbers next to theirs. So the room argues about a number from a neighbor's driveway, and the budget vote turns into a vote on a rumor.
Here is how to answer that question with facts, from free public records and one email, in about two weekends. It works whether your dues turn out high, low or right. It also protects the board from the most expensive answer of all: "fine, we'll cut to sixty," when Oakmont's sixty is a reserve fund that cannot pay for its next roof.
Before you start: What to pull first
You need your own numbers before anyone else's. Pull these five things and put them in one folder:
- This year's adopted budget and last year's actual spending (the year-end report, not the budget).
- The current reserve study, or the most recent one, with its percent-funded figure.
- The latest bank statements for the operating and reserve accounts.
- The dues roll or aging report: how many homes are behind, and by how long.
- The three largest contracts the association pays (usually landscaping, insurance and either management or utilities).
If one of these does not exist, write that down. "We have no reserve study" is the first finding, and it matters more than anything a neighbor's budget will tell you.
Seven steps, about two weekends.
- Step 1: Six per-home numbers
- Step 2: Three to five peers
- Step 3: The public numbers
- Step 4: Ask to trade
- Step 5: Reserves against the line
- Step 6: Mark the gaps
- Step 7: One page
Step 1 — Turn the budget into six per-home numbers
A 300-home association will always spend more than a 60-home one. That tells you nothing. Divide by homes and the comparison starts to mean something. Work out these six from the folder:
- Dues per home, per month. Annual assessment income divided by the number of homes, divided by 12. Use what owners are billed, not a figure from the budget's front page.
- Operating spending per home, per year. Last year's actual operating expenses, without the reserve contribution, divided by homes.
- The reserve share of the budget. The yearly contribution to reserves divided by the total budget. A budget that puts 5% into reserves and one that puts 25% are different plans, even at the same dues.
- Percent funded. From the reserve study: the reserve balance divided by the fully funded balance (what the study says should be set aside today).
- Homes 60 or more days behind, as a share of all homes.
- The three biggest contracts, per home, per year. Each contract's yearly cost divided by homes.
Write them in one column with the date you worked them out. Done when: one column of six numbers exists, and a second board member has checked each one.
Step 2 — Choose three to five true peers
The wrong peer gives the wrong answer with total confidence. The owner who says "Oakmont pays sixty" may be comparing a pool, a clubhouse and private streets with a subdivision that has an entrance sign and a retention pond.
A true peer passes all five of these tests:
- The same kind of homes. Single-family with single-family; condos and townhomes with their own. A condo fee can cover a roof, a building's insurance and an elevator. Single-family dues usually do not.
- A similar number of homes. Roughly half to double yours. Small associations cannot spread fixed costs like insurance and audits as thinly.
- The same amenities. A pool alone can be a large share of a small budget. Count pools, clubhouses, gates, private roads and staffed amenities.
- The same county or metro. Labor, insurance and utilities are priced locally.
- A similar age. A 25-year-old community is replacing roofs, roads and pool plaster. A 5-year-old one is not, yet.
Write the list, with one line per peer saying why it belongs. Three good peers beat ten loose ones. Done when: three to five communities are on the list, and each passes all five tests.
Step 3 — Pull the public numbers
Most boards assume a neighbor's finances are private. Some of them are public, and the rest are closer than you think. Three free sources, in this order:
The county median, from the Census. Starting with its 2024 estimates, the Census Bureau's American Community Survey reports what owners pay in HOA and condo fees. Table B25143 gives the median for counties of 65,000 people or more. It mixes condo fees with single-family dues, so treat it as a fence, not a target: if your single-family dues are far above the county median, the reason should be on your amenity list. How to find your county's number in five minutes walks through the search.
Any peer's tax return, on ProPublica. This is the one most boards have never heard of. An association recognized as tax-exempt files a Form 990, and the IRS requires exempt organizations to make their annual returns available for public inspection. ProPublica's free Nonprofit Explorer puts those returns online: total revenue, total expenses, assets and liabilities, by year. A search for "homeowners association" there returned 1,325 organizations on October 25, 2026.
1,325 organizations come up when you search "homeowners association" on ProPublica's free Nonprofit Explorer, each with the revenue, expenses, assets and liabilities from its filed returns. — ProPublica Nonprofit Explorer, searched October 25, 2026
Two cautions. An association that files its taxes on Form 1120-H, the IRS's income tax return for homeowners associations, files no Form 990, so there is no 990 to read. And a small exempt association with gross receipts normally $50,000 or less can file the short e-Postcard (Form 990-N) instead, which carries no budget. So search each peer by its legal name; when it is there, divide its revenue and expenses by its homes and you have two of your six numbers for free.
The budget its own owners already hold. Many associations send owners the budget every year. Plenty of associations also post budgets and annual meeting packets on their websites. If a friend, a colleague or a board member's sister lives in a peer community, they may have this year's budget in a kitchen drawer.
Done when: every peer has a row, every cell you could fill from these three sources is filled, and each one names where it came from.
Step 4 — Ask the neighbors to trade
The fastest benchmark is a fellow treasurer. Boards rarely ask each other, yet a specific ask that comes with your own numbers first is easy to say yes to.
Send this, or something like it, to the board contact of each peer:
We are comparing a few per-home numbers with communities like ours before our budget meeting. Here are our six. Would you share yours? We will send you the full comparison when it is done.
Offer your column first. Name the six numbers exactly, so nobody has to send a whole budget. Promise the finished comparison back, and keep the promise, because next year you will want to ask again.
Some will not answer. That is fine. Two replies plus the public numbers are enough to see a pattern. Done when: every peer has been asked once, in writing, with your own column attached.
Step 5 — Hold reserves against the line, not the neighbors
This is the step that keeps a benchmark from doing damage. On every other number, being near the peers is reassuring. On reserves, being near the peers can mean being in trouble together.
Association Reserves, a reserve-study firm, sorts percent funded into three bands: 0 to 30% weak, 30 to 70% fair, 70% and up strong. Across more than 100,000 reserve studies it has prepared, most communities sat below the strong line.
74% of associations in more than 100,000 reserve studies were funded below the 70% "strong" line. — Association Reserves, November 2025 analysis
So if your percent funded matches your peers' and all of you sit at 35%, the benchmark has not told you that you are fine. It has told you that the neighborhood shares a bill nobody has paid yet. Read your own reserve number against the 70% line first, then look at the peers.
What percentage your reserve fund should be funded at
The same goes for the cheapest peer's dues. If Oakmont pays sixty dollars and puts almost nothing into reserves, its lower dues are a delay, not a saving. Done when: your percent funded is written next to its band, and every peer's reserve share is marked "known" or "not known."
Step 6 — Mark only the gaps that matter
Now you have a small table: your six numbers across the top row, each peer below, and the county median and the 70% line as fixed marks. Most differences will be small and mean nothing. A useful rule of thumb: mark a gap only when your per-home number is more than 20% above or below the middle of your peers.
For every marked gap, write one sentence that names the cause. If you cannot name one, that is the question for the board.
Here is how it reads in practice. An illustrative example, not a real association: the single-family community from the opening, 120 homes, pays $85 a month. Its peers sit between $62 and $78. That is a marked gap. The cause sentence: "We have the only pool in the peer set, and the pool contract is $71 a home a year." The same community's landscaping is $190 a home a year against peers near $140, another marked gap, with no cause anyone can name. That one goes to the next bid, using the same steps the board uses to bid out any contract. Its percent funded is 38%, fair but well under the line, so the board's answer to the owner in the third row is not "we will cut dues." It is "our dues pay for a pool the others do not have, we are rebidding landscaping, and our reserves need more, not less."
Done when: every marked gap has either a cause sentence or a named next step, such as a bid, a question to a vendor or a reserve-study update.
Step 7 — Put it on one page for the board
The comparison only works if the whole board, and then the owners, can read it in two minutes. One page:
- The six numbers, yours and the peers', with the source under each.
- The county median and the 70% reserve line, drawn as fixed marks.
- The marked gaps, each with its cause sentence or next step.
- One plain sentence the president can say at the meeting.
In the illustrative example, that sentence reads: "Our dues are $85 a month. Communities like ours pay $62 to $78. The difference is our pool. Our landscaping is high, and we are rebidding it. Our reserves are 38% funded, so we are not cutting what goes into them."
Put the page in the board packet before the budget meeting, not after the question is asked. Done when: the page is in the packet, and the president has read the sentence out loud once.
How to tell it worked
You will know it worked if three things are true by the end of the budget meeting:
- Every dues question was answered with a peer number and a cause, not a defense.
- At least one marked gap has an owner and a date (a bid, a call, a study).
- Nobody proposed cutting the reserve contribution to match a cheaper neighbor.
Save the table. Next year it takes one weekend, because the peers and the sources are already chosen, and a number that moved 20% in a year is worth a question by itself.
Frequently asked questions
How do I compare my HOA's finances to other HOAs? Turn your budget into six per-home numbers (dues, operating spending, the reserve share of the budget, percent funded, the share of homes 60 days behind, and the three biggest contracts), then put three to five true peers beside them. Fill the peers from the Census county median, any peer's Form 990 on ProPublica's Nonprofit Explorer, and the budgets their own owners receive. Mark only gaps over about 20%, and name a cause for each.
Where can I find another HOA's budget? Ask its board directly, offering your own numbers first. Look for budgets or annual meeting packets on its website, or ask someone who lives there, since many associations send owners the budget each year. If the association is tax-exempt and files a Form 990, its revenue, expenses, assets and liabilities are on ProPublica's free Nonprofit Explorer.
Are our HOA dues too high? Not because they are above a neighbor's. Compare per-home dues with true peers (same kind of homes, a similar count, the same amenities and county) and with your county's Census median. If yours are higher, the reason should be on your amenity list or your reserve contribution. If you cannot name the reason, that is the question to answer.
What is a good percent funded for an HOA reserve? Association Reserves calls 70% and up strong, 30 to 70% fair, and under 30% weak. In its November 2025 analysis of more than 100,000 reserve studies, 74% of associations were below 70%, so match the line, not the neighbors.
Can I see another HOA's tax return? Sometimes. A tax-exempt association's Form 990 must be available for public inspection, and ProPublica's Nonprofit Explorer shows many of them. An association that files Form 1120-H, the homeowners association income tax return, has no Form 990 to see, and a small one that files only the e-Postcard (Form 990-N) shows no budget.